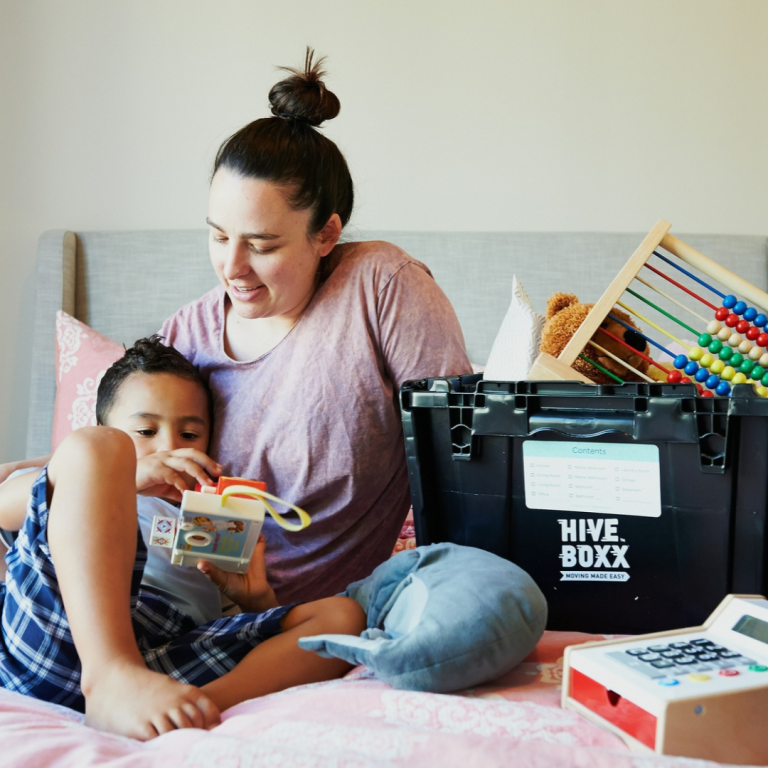
When you have young kids, it’s pretty common for one parent to be earning most of the household income while the other is at home, on parental leave or working fewer hours.
And when it comes to insurance, the conversation usually starts with protecting the person bringing home the pay cheque.
That makes sense. But what about the parent who’s doing the school runs, looking after the kids, keeping the household running and somehow remembering when everyone needs new shoes?
Their contribution might not come with a salary, but it certainly has financial value.
So, how should families think about insurance when one parent earns more than the other?
Protecting the main income
If your household relies heavily on one person’s income, it’s worth thinking about what would happen if they couldn’t work for an extended period.
The mortgage, groceries, power bills and childcare costs don’t stop just because someone’s income does.
This is where income protection insurance or mortgage protection insurance may be worth considering.
Depending on the policy, these types of cover can provide regular payments if illness or injury prevents the insured person from working.
The important thing is understanding what your household needs to keep running, rather than simply insuring the biggest possible amount.
But what about the stay-at-home parent?
This is the part families sometimes overlook.
Imagine the parent who normally looks after the children suddenly couldn’t do so because of a serious illness, or passed away.
The working parent might need to reduce their hours, take extended time off or arrange additional childcare.
And anyone who’s paid for childcare in New Zealand knows it isn’t cheap.
Even without a regular income to replace, there could be significant financial consequences for the family.
That’s why life insurance for stay-at-home parents can be just as important to consider.
It isn’t necessarily about replacing a salary. It’s about giving the family financial breathing room to adjust.
Does the stay-at-home parent need income protection?
Not necessarily.
Income protection insurance generally covers a portion of eligible earnings, so a parent who isn’t currently earning an income may not qualify for this type of cover.
However, there are other options worth discussing.
Life insurance can provide a lump sum if the insured person dies.
Trauma insurance can provide a lump sum if they’re diagnosed with a specified serious medical condition and meet the policy’s requirements.
Health insurance may help with access to eligible private medical treatment, depending on the policy.
Each protects against something different, and not every family needs every type.
What if both parents work, but one earns much less?
The same thinking applies.
It’s easy to focus on the higher earner, but consider what the lower earner’s income contributes.
Does it cover groceries? Childcare? Savings? The extra mortgage repayments?
And if that parent couldn’t work, would the other need to change their working arrangements?
The answer might change how you prioritise your insurance.
So, what insurance should your family actually have?
There’s no one-size-fits-all answer.
A useful starting point is to ask yourselves three questions:
- What income does our family rely on? Think about how you’d manage if one or both incomes stopped.
- What unpaid work does our family rely on? Consider childcare, school runs and everything else that keeps your household functioning.
- What financial support would we need if something changed? That might mean covering the mortgage, paying for childcare or simply having time to adjust.
You might discover you already have enough cover. You might find a gap you hadn’t considered.
Either way, understanding what you’re protecting is far more useful than simply taking out another insurance policy.
A little help from Canvas
At Canvas Insurance, we help Kiwi families work through these questions without the confusing insurance jargon.
Sometimes that means recommending cover. Other times, it means helping you understand what you already have and whether it still makes sense for your family.
Because the goal isn’t to have the most insurance. It’s to protect the things your family relies on most.
Have a chat with Kris about your family’s insurance options. No pressure, just practical advice.
FAQs
Does a stay-at-home mum or dad need life insurance in NZ?
It can be worth considering. Even without a salary, a stay-at-home parent provides childcare and household support that could be expensive or difficult to replace. The right amount of life insurance depends on your family’s circumstances.
Can a stay-at-home parent get income protection insurance?
Generally, income protection is designed to replace a portion of eligible earnings. If you’re not earning an income, you may not qualify. An insurance adviser can help explain what alternatives are available.
Should both parents have life insurance?
Many families benefit from considering cover for both parents, even if one earns significantly less. The amount and type of cover should reflect each person’s financial contribution and the support the family would need if they died.
What insurance is most important for young families in NZ?
It depends on your income, mortgage, dependants, existing cover and budget. Life insurance, income protection, mortgage protection and trauma insurance are all worth understanding, but that doesn’t mean you need all of them.